|
The Week Ahead: Highlights
Asia-Pacific Preview
Aussie Jobs Report in Focus as
Markets Await Next RBA Rate Hike
By Brian Jackson, Econoday Economist
Australian labour market data for September will be
published in the week ahead. Conditions were steady in August, with employment
rebounding from a previous fall and the unemployment rate increasing slightly.
This was consistent with the assessment made by the Reserve Bank of Australia
at its most recent policy meeting in late September, with officials judging
that labour market conditions had eased broadly as expected in recent months.
Officials raised policy rates at that meeting and stressed that they would
increase policy rates further if required, and next weeks data will likely do
little to shift expectations for the next policy meeting in early November.
Also scheduled for release in the week ahead are the minutes of the last RBA
meeting and the NAB business sentiment survey.
Indian inflation data may do more to shape expectations for
the Reserve Bank of India. At the RBI meeting this week, officials hiked rates
by 25 basis points, the first increase since 2023, noting the impact on the
inflation outlook of the Iran conflict and adverse rainfall patterns in the
current monsoon season. Annual headline and core inflation are now forecast to
be 5.2 percent and 4.4 percent respectively, up from the previous forecasts of
5.0 percent and 4.3 percent respectively. Both consumer and wholesale price
data for September will be published in the week ahead.
Chinese inflation data for September are also scheduled for
release. Headline CPI inflation in China picked up from a six-month low in
August, largely reflecting a rebound in food prices, while producer price
inflation remained near multi-year highs. Next weeks data may show ongoing
strength in producer prices, with PMI survey data published earlier this month
showing stronger growth in input costs in the Chinese manufacturing sector in
September.
China, India and Singapore will publish trade data in the
week ahead. South Korea and Taiwan have already reported September trade data,
with both recording another month of very strong growth in AI-related exports.
PMI surveys have also generally shown solid growth in new export orders across
the region in September.
US Preview
Inflation Reports Key to FOMC
Policy Outlook
By Theresa Sheehan, Econoday Economist
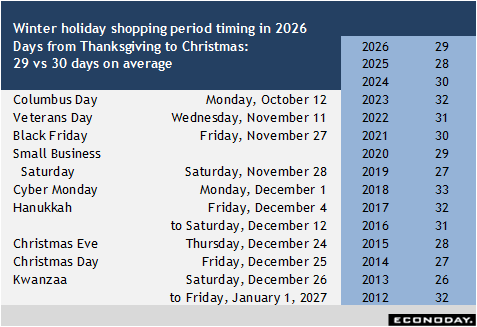
Monday, October 12 is a federal holiday (Columbus
Day/Indigenous Peoples Day) with a full bond market close. However, stock
markets will be open. The holiday is not widely observed, and most businesses
will operate on normal hours. While the winter holidays are still some weeks
distant, many retailers will start their seasonal sales in earnest with a
three-day weekend to kick things off early for shoppers. Discounts and
promotions may be prominent in anticipation of a lackluster holiday when
consumer dollars are more limited for discretionary spending.
The economic information in the week will be important to
the upcoming FOMC meeting on October 27-28. Foremost will be the inflation
reports for September. The consumer price index (CPI), final-demand producer
price index (PPI), and import and export price indexes will be released at 8:30
ET on Wednesday, Thursday, and Friday, respectively. Energy costs will dominate
the data, especially for motor fuels that took a big jump higher early in the
month that was especially noticeable for diesel prices. For the CPI and PPI,
earlier price increases in August will start to pass through to costs for
services like transportation. With inflation pressures not letting up, the FOMC
deliberations will focus on price stability despite the slightly softer
employment numbers.
The dollar amount of retail sales for September at 8:30 on
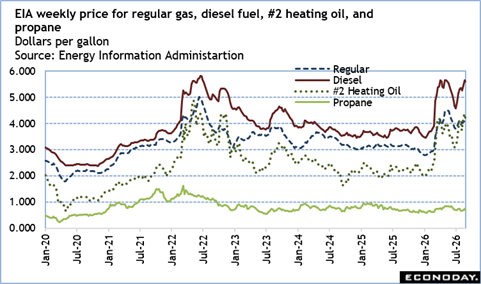
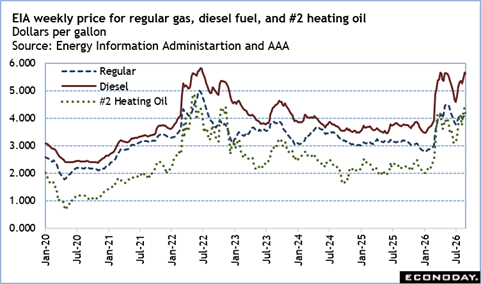
Thursday will also feature the energy story. Consumers paid higher prices for
gasoline in September with the EIA price per gallon of regular peaking at
$4.478 in the September 21 week. The increase in diesel costs has less direct
impact on retail but earlier rises in transportation for goods and services may
push some spending higher from pass through. Diesel prices were already sharply
higher in August before peaking at $6.529 per gallon in the September 21 week.
Gasoline sales typically account for under 10 percent of total retail sales but
this price is going up at a time of year when prices normally ease with the
changeover to winter fuel formulations.
More important to household spending will be rising costs
for #2 heating oil and propane which are important to home heating as the
colder weather approaches. These sales fall within the category of nonstore
retailers which also includes etailers. The EIA price for a gallon of #2
heating oil hit $5.025 in the September 21 week and the price of a gallon of
propane steadily climbed during September to reach $0.878 in the September 28
week.
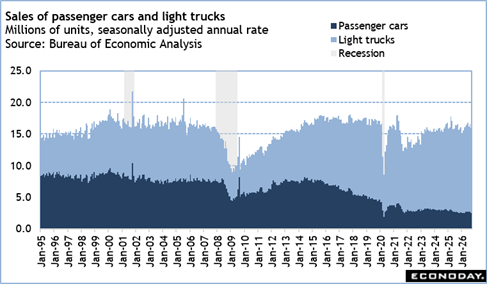
Unit sales of motor vehicles were essentially unchanged in
September at 16.0 million at a seasonally adjusted annual rate, so the dollar
value of motor vehicles wont be much of a factor in determining the underlying
pace of retail sales for September.
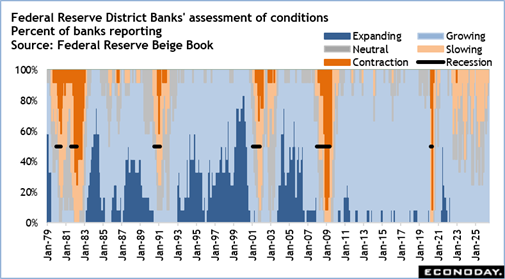
Also important to the upcoming FOMC deliberations will be
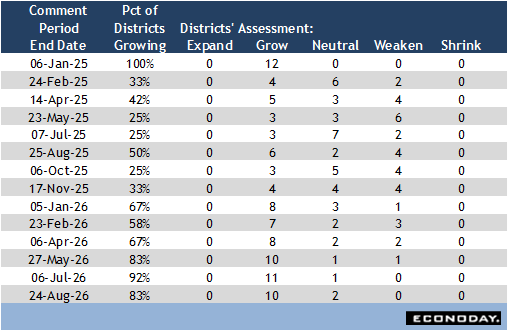
the content of the Beige Book set for release at 14:00 ET on Wednesday. This
one will comment on conditions from roughly late August through late September.
The prior three Beige Books pointed to modest-to-moderate expansion as
prevailing across the 12 Fed districts. This upcoming one will coincide with
the rises in energy costs and broadening inflation worries, as well as reflect
the direction of the labor market and employee compensation. It is likely to be
somewhat less positive than recent Beige Books.
The Week Ahead: Econoday Consensus Forecasts
Monday
India CPI for September (Mon 1600 IST; Mon 1030 GMT;
Mon 0630 EDT)
Consensus Forecast, Y/Y: 5.57%
Consensus Range, Y/Y: 4.90% to 5.70%
The consensus sees energy costs increasing annual CPI
inflation to 5.57 percent on year in September from 4.82 percent in August.
Tuesday
Japan PPI for September (Tue 0750 JST; Mon 2350 GMT; Mon
1950 EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.5% to 0.7%
Consensus Forecast, Y/Y: 7.6%
Consensus Range, Y/Y: 7.6% to 7.8%
Japans producer price inflation is expected to stay
elevated in September, holding close to its highest level in more than three
years as prolonged geopolitical tensions in the Middle East kept crude oil,
petroleum products and chemical prices high. The yens weakness also continued
to put upward pressure on import costs, lifting the countrys producer prices.
The Corporate Goods Price Index (CGPI) is projected to rise
7.6 percent on the year in September, little changed from a month earlier. This
would mark a 67th straight month of year-on-year rise, or over five and a half
years of increase. In August, the index eased to a 7.6 percent rise from Julys
7.7 percent, which was the highest since February 2023, when it rose 8.4
percent.
On a monthly basis, the CGPI is expected to rise 0.5 percent
in September, marking its first increase in two months after falling 0.2
percent in August, which was the first monthly decline in 12 months.
Germany CPI for September (Tue 0800 CEST; Tue 0600
GMT; Tue 0200 EDT)
Consensus Forecast, M/M: 0.6%
Consensus Range, M/M: 0.4% to 0.6%
Consensus Forecast, Y/Y: 3.3%
Consensus Range, Y/Y: 3.3% to 3.3%
Consensus Forecast, HICP - M/M: 0.6%
Consensus Range, HICP - M/M: 0.6% to 0.6%
Consensus Forecast, HICP - Y/Y: 3.3%
Consensus Range, HICP - Y/Y: 3.3% to 3.3%
Forecasters expect no revision in the final from the flash
at 0.6 percent and 3.3 percent for both CPI and HICP.
US NFIB Small Business Optimism Index for September (Tue
0600 EDT; Tue 1000 GMT)
Consensus Forecast, Index: 98.0
Consensus Range, Index: 95.0 to 98.4
A slightly weaker 98.0 is the call, down from 98.7 in
August.
US Existing Home Sales for September (Thu 1000
EDT; Thu 1400 GMT)
Consensus Forecast, Annual Rate: 3.965 M
Consensus Range, Annual Rate: 3.890 M to 4.000 M
The consensus sees a softer 3.965 million for September from
3.980 in August as rising mortgage rates hold down demand.
Wednesday
Singapore GDP for Third Quarter (Wed 0830 SGT; Wed
0030 GMT; Tue 2030 EDT)
Consensus Forecast, Q/Q: 1.4%
Consensus Range, Q/Q: 1.0% to 1.4%
Consensus Forecast, Y/Y: 5.1%
Consensus Range, Y/Y: 4.9% to 5.4%
Growth expected at 1.4 percent on quarter and 5.4 percent on
year for Q3 versus 1.4 percent and 5.9 percent in Q1.
China CPI for September (Wed 0930 CST; Wed 0130 GMT;
Tue 2130 EDT)
Consensus Forecast, Y/Y: 1.0%
Consensus Range, Y/Y: 1.0% to 1.1%
The consensus looks for inflation slightly faster at 1.0
percent in September, up from 0.8 percent in August. Still not much.
China PPI for September (Wed 0930 CST; Wed 0130 GMT;
Tue 2130 EDT)
Consensus Forecast, Y/Y: 4.5%
Consensus Range, Y/Y: 4.2% to 4.5%
The consensus sees wholesale prices surging by 4.5 percent
in September versus 3.8 percent in August, reflecting rising energy and
commodities prices.
China Merchandise Trade for September (ANYTIME)
Consensus Forecast, Balance of Trade: $118.0 B
Consensus Range, Balance of Trade: $ 108 B to $118.1
B
Consensus Forecast, Imports - Y/Y: 24.0%
Consensus Range, Imports - Y/Y: 23.1% to 27.2%
Consensus Forecast, Exports - Y/Y: 25.3%
Consensus Range, Exports - Y/Y: 23.5% to 25.7%
The trade surplus is seen at $118.0 billion in September
versus $119.1 billion inAugust as both exports and imports continue to surge
from a year ago.
India Wholesale Price Index for September (Wed 1200
IST; Wed 0600 GMT; Wed 0200 EDT)
Consensus Forecast, Y/Y: 10.52%
Consensus Range, Y/Y: 10.18% to 12.0%
WPI inflation expected to accelerate to 10.52 percent from
9.92 percent in August.
US CPI for September (Wed 0830 EDT; Wed 1230 GMT)
Consensus Forecast, CPI - M/M: 0.6%
Consensus Range, CPI - M/M: 0.5% to 0.7%
Consensus Forecast, CPI - Y/Y: 3.6%
Consensus Range, CPI - Y/Y: 3.3% to 3.7%
Consensus Forecast, Ex-Food & Energy - M/M: 0.2%
Consensus Range, Ex-Food & Energy - M/M: 0.2% to 0.3%
Consensus Forecast, Ex-Food & Energy - Y/Y: 2.5%
Consensus Range, Ex-Food & Energy - Y/Y: 2.4% to 2.5%
Energy costs continue to play havoc: a 0.6 percent rise is expected
on the month and 3.6 percent on year.
Thursday
Japan Machinery Orders for August (Thu 0850 JST; Wed
2350 GMT; Wed 1950 EDT)
Consensus Forecast, M/M: 3.4%
Consensus Range, M/M: 2.4% to 4.6%
Consensus Forecast, Y/Y: 15.3%
Consensus Range, Y/Y: 14.3% to 18.7%
Japans core machinery orders are expected to rebound on the
month in August, backed by signals of strong domestic machine tool orders. The
general uptrend in machinery orders is seen staying in place amid solid capital
investment plans and firm global demand related to artificial intelligence,
prompting orders for semiconductor manufacturing equipment and other AI-related
items.
August machinery orders, a key leading indicator of business
investment in equipment and software, are forecast to rise 3.4 percent on the
month after falling 3.7 percent a month earlier.
In July, the decline was led by lower orders from nonferrous
metal producers for nuclear power facilities and computers, computer and
telecommunications equipment makers for motors and computers, and real estate
firms, partly reflecting a payback after a surge in orders from those
industries in the previous month.
Core machinery orders are expected to post double-digit
annual growth for a third straight month in August, rising 15.3 percent from
11.2 percent in July. They rose 16.9 percent in June.
Australia Labour Force Survey for September (Thu 1130
AEDT; Thu 0030 GMT; Thu 2030 EDT)
Consensus Forecast, Employment - M/M: 20K
Consensus Range, Employment - M/M: 15.9K to
35K
Consensus Forecast, Unemployment Rate: 4.6%
Consensus Range, Unemployment Rate: 4.5% to 4.7%
A modest 20K rise is expected with the jobless rate flat at
4.6%.
UK Monthly GDP for August (Thu 0700 BST; Thu 0600
GMT; Thu 0200 EDT)
Consensus Forecast, M/M: -0.1%
Consensus Range, M/M: -0.3% to 0.1%
Consensus Forecast, Q/Q: 0.5%
Consensus Range, Q/Q: 0.2% to 0.5%
Monthly GDP expected to contract by 0.1 percent in August.
UK Industrial Production for August (Thu 0700 BST;
Thu 0600 GMT; Thu 0200 EDT)
Consensus Forecast, Industrial Production - M/M: -0.1%
Consensus Range, Industrial Production - M/M: -0.2%
to -0.1%
Consensus Forecast, Industrial Production - Y/Y: 0.7%
Consensus Range, Industrial Production - Y/Y: 0.5% to
1.5%
Consensus Forecast, Manuf. Production - M/M: 0.0%
Consensus Range, Manuf. Production - M/M: -0.5% to 0.3%
Consensus Forecast, Manuf. Production - Y/Y: 0.7%
Consensus Range, Manuf. Production - Y/Y: 0.5% to 1.5%
Industrial production expected down 0.1 percent with manufacturing
flat on the month.
France CPI for September (Thu 0845 CEST; Thu 0645
GMT; Thu 0245 EDT)
Consensus Forecast, M/M: -0.3%
Consensus Range, M/M: -0.4% to -0.3%
Consensus Forecast, Y/Y: 3.0%
Consensus Range, Y/Y: 3.0% to 3.4%
Consensus Forecast, HICP - M/M: -0.4%
Consensus Range, HICP - M/M: -0.4% to
Consensus Forecast, HICP - Y/Y: 3.4%
Consensus Range, HICP - Y/Y: 3.4% to 3.4%
Eurozone Industrial Production for August (Thu 1100
CEST; Thu 0900 GMT; Thu 0500 EDT)
Consensus Forecast, M/M: 0.1%
Consensus Range, M/M: -0.1% to 0.5%
Consensus Forecast, Y/Y: 0.1%
Consensus Range, Y/Y: -0.1% to 0.3%
Industrial production seen up 0.1 percent on the month after
declining 0.1 percent in July.
US Jobless Claims for Week of October 10 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 200K
Consensus Range, Initial Claims - Level: 194 K to 201
K
Claims expected back at 200K from 197K last week.
US PPI-Final Demand for September (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, PPI-FD - M/M: 0.5%
Consensus Range, PPI-FD - M/M: 0.4% to 0.7%
Consensus Forecast, PPI - Y/Y: 5.4%
Consensus Range, PPI - Y/Y: 5.3% to 5.9%
Consensus Forecast, Ex-Food & Energy - M/M: 0.3%
Consensus Range, Ex-Food & Energy - M/M: 0.3% to 0.3%
Consensus Forecast, Ex-Food & Energy - Y/Y: 4.5%
Consensus Range, Ex-Food & Energy - Y/Y: 4.4% to 4.7%
PPI expected up 0.5 percent and 5.4 percent on year for
September, lifted by energy costs.
US Retail Sales for September (Thu 0830 EDT; Thu 1230
GMT)
Consensus Forecast, Retail Sales - M/M: 0.3%
Consensus Range, Retail Sales - M/M: 0.0% to 0.4%
Consensus Forecast, Ex-Vehicles - M/M: 0.4%
Consensus Range, Ex-Vehicles - M/M: -0.1% to 0.7%
Consensus Forecast, Ex-Vehicles & Gas - M/M: 0.2%
Consensus Range, Ex-Vehicles & Gas - M/M: 0.2% to
0.2%
A modest 0.3 percent increase for sales (in nominal terms)
is the call after a big 1.2 percent jump in August.
Canada Manufacturing Sales for August (Thu 0830 EDT; Thu
1230 GMT)
Consensus Forecast, M/M: 1.1%
Consensus Range, M/M: 1.1% to 1.3%
Forecasters agree with the Stats Canada preliminary estimate
of up 1.1 percent.
US Philadelphia Fed Manufacturing Index for October (Thu
0830 EDT; Thu 1230 GMT)
Consensus Forecast, Index: 28.5
Consensus Range, Index: 25.0 to 34.0
The consensus looks for the index at 28.5 in October, still
a robust expansion but down from 37.8 in September.
US Empire State Manufacturing Index for October (Thu
0830 EDT; Thu 1230 GMT)
Consensus Forecast, Index: 10.5
Consensus Range, Index: 7.0 to 15.0
The index is expected in moderate expansion at 10.5 for
October versus 7.60 in September.
US Business Inventories for May (Thu 1000 EDT; Thu
1400 GMT)
Consensus Forecast, M/M: 0.4%
Consensus Range, M/M: 0.3% to 0.9%
Inventories seen up 0.4 percent on the month.
Friday
Italy CPI for September (Fri 1100 CEST; Fri 0900 GMT;
Fri 0500 EDT)
Consensus Forecast, M/M: 0.7%
Consensus Range, M/M: 0.7% to 2.0%
Consensus Forecast, Y/Y: 4.2%
Consensus Range, Y/Y: 4.1% to 4.2%
Eurozone HICP for September (Fri 1100 CEST; Fri 0900
GMT; Fri 0500 EDT)
Consensus Forecast, HICP - Y/Y: 3.8%
Consensus Range, HICP - Y/Y: 3.8% to 3.8%
Consensus Forecast, Narrow Core - Y/Y: 2.5%
Consensus Range, Narrow Core - Y/Y: 2.5% to 2.5%
The consensus looks for no revision in the final from the
flash with HICP up 3.8 percent on year in September and narrow core up 2.5
percent.
Canada Housing Starts for September (Thu 0815 EDT;
Thu 1215 GMT)
Consensus Forecast, Annual Rate: 220K
Consensus Range, Annual Rate: 210K to 230K
Starts expected slightly lower at 220K rate in September
versus 229K in August.
US Imports and Export Prices for September (Fri
0830 EDT; Fri 1230 GMT)
Consensus Forecast, Import Prices - M/M: 0.6%
Consensus Range, Import Prices - M/M: 0.4% to 0.8%
Consensus Forecast, Export Prices - M/M: 1.0%
Consensus Range, Export Prices - M/M: 0.4% to 1.3%
Import prices seen up 0.6 percent and export prices up 1.0
percent on month in September.
US Industrial Production for September (Fri
0915 EDT; Fri 1330 GMT)
Consensus Forecast, Industrial Production - M/M: 0.4%
Consensus Range, Industrial Production - M/M: 0.1% to
0.6%
Consensus Forecast, Capacity Utilization Rate: 76.5%
Consensus Range, Capacity Utilization Rate: 76.4% to 76.6%
Output seen up 0.4 percent on the month, a decent gain
reflecting a moderately expansionary ISM manufacturing index for September.
Capacity is expected at 76.5. percent versus 76.3 a month earlier.
|