|
The Week Ahead: Highlights
Asia-Pacific Preview
Waiting for the RBA Rate Move
By Brian Jackson, Econoday Economist
The Reserve Bank of Australias policy meeting is the major
focus in the Asia-Pacific region in the week ahead. Officials raised policy
rates for the fourth time this year at their last meeting in late-September,
judging that "some of the upside risks to inflation are materialising"
and expressing their concern that inflation "is still too high". They
also stressed that they will do what they consider necessary to deliver price
stability and full employment, implying that they are ready to increase rates
again if inflationary pressures do not start to moderate soon. The Econoday
consensus looks for the RBA to raise rates by 25 basis points.
Inflation data published this week showed underlying
measures of inflation were steady in September, with the trimmed mean measure
up slightly from 3.5 percent to 3.6 percent and the weighted median measure
falling from 3.6 percent to 3.4 percent. Headline inflation, however, rose from
4.0 percent in August to 4.3 percent in September, further above the target
range of two percent to three percent. That may be enough to prompt another
rate hike next week. Monthly household spending and trade data for September
will be published after the RBA meeting.
Monthly PMI surveys for the region will also be watched
closely. September surveys again showed the impact of both the Iran conflict
and ongoing strength in AI-related demand. The influence of both factors on
activity, sentiment and cost pressures across the region will likely remain
evident in the October surveys.
South Korea, Taiwan and Thailand will all publish inflation
data in the week ahead. The central banks for all three countries left policy
rates on hold at their most recent meetings, but officials at the Bank of Korea
have expressed concern about the inflation outlook in recent months and have
indicated that policy tightening will be considered in upcoming meetings. South
Koreas headline inflation moderated from 3.1 percent in August to 2.9 percent
in September, but remained well above the two percent target. New Zealand will
also publish quarterly labour market data in the week ahead.
US Preview
Nonfarm Payrolls, Job Openings Reports in Focus
By Theresa Sheehan, Econoday Economist
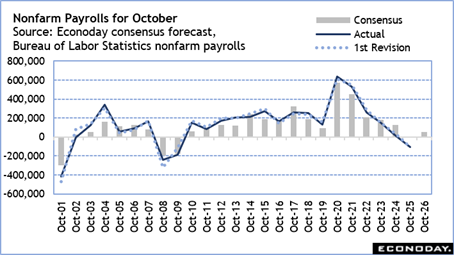
The November 2 week includes several reports covering the
labor market. The most important is the October employment situation at 8:30 ET
on Friday.
Early forecasts for the change in nonfarm payrolls center
around an increase of about 50,000. This is a temperate gain that would be
enough to support the current how hire, low fire balance in the labor market.
There is a five-week survey reference period between the September and October
surveys which means that this report should capture a good snapshot of hiring
in this month. October can be affected by seasonal hiring for sectors like
retail and delivery services in advance of the winter holidays. This year many
businesses reduced their hiring plans, in part from a limited labor supply and
in part about concerns for consumer spending when inflation is eating up more
discretionary income for moderate and lower income households.
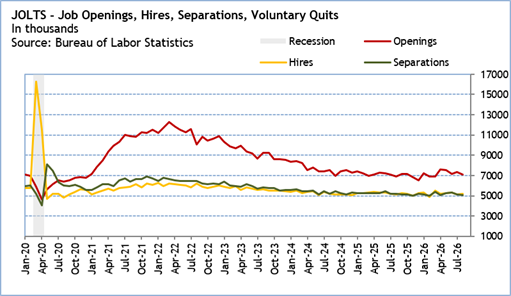
Also getting close scrutiny will be the September data on
job openings and labor turnover (JOLTS) on Tuesday at 10:00 ET. Although these
numbers lag the upcoming employment data, it will provide a sense if the job
market is providing opportunities or if the number of jobs open is contracting
and/or if hiring continues but at a sluggish pace. Jobs open and new hires have
tended to be a few narrow sectors in recent months, most notably healthcare. If
that doesnt change in September, the labor market remains good, but only for
certain skilled workers.
This week and for the next few months it will be time to watch
for distortions in seasonal adjustment factors in the economic data. The 43-day
federal government shutdown of October 1 to November 12, 2025, will mean that
data for October and November of this year may follow normal behavior in
comparison. In some instances, there will be no data with which to make a
comparison. It will probably be necessary to look at indicator performance for
October and November as a unit to gauge what the present reports are saying
about the economy.
The Week Ahead: Econoday Consensus Forecasts
Monday
China PMI Manufacturing for October (Mon 0945 CST;
Mon 0145 GMT; Sun 2045 EST)
Consensus Forecast, Index: 52.0
Consensus Range, Index: 51.7 to 52.2
A flat showing is expected with the index at 52.0 in October
versus 52.1 in September. That would suggest very modest continuing expansion
in business activity.
Germany Retail Sales for September (Mon 0800 CET; Mon
0700 GMT; Mon 0200 EST)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: -1.0% to 0.8%
Consensus Forecast, Y/Y: -0.2%
Consensus Range, Y/Y: -0.8% to 0.2%
Sales expected up again on the month by 0.5 percent in
September after a big 1.3 percent jump in August. On year, the consensus looks
for a 0.2 percent decline in September after minus 0.4 percent in August.
France PMI Manufacturing Final for October (Mon 0850
CET; Mon 0750 GMT; Mon 0250 EST)
Consensus Forecast, Index: 49.3
Consensus Range, Index: 49.3 to 49.3
The consensus looks for no revision in the final from the
flash at 49.3 for October, which suggests marginal contraction in business
activity. That is down from 50.6 in September and illustrates how France is
lagging Germany where the expansion is picking up a bit of speed.
Germany PMI Manufacturing Final for October (Mon 0955
CET; Mon 0855 GMT; Mon 0355 EST)
Consensus Forecast, Index: 54.2
Consensus Range, Index: 54.2 to 54.2
The consensus looks for no revision in the final from the
flash at 54.2 for October, which suggests moderate growth in business activity,
up slightly from 53.9 in September, despite elevated input prices.
Eurozone PMI Manufacturing Final October (Mon 1000
CET; Mon 0900 GMT; Mon 0400 EST)
Consensus Forecast, Index: 52.4
Consensus Range, Index: 52.4 to 52.4
The consensus looks for no revision in the final from the
flash at 52.4 for October, which suggests modest growth in business activity,
off slightly from 52.9 in September.
UK PMI Manufacturing Final for October (Mon 0930 GMT;
Mon 0430 EST)
Consensus Forecast, Index: 52.8
Consensus Range, Index: 52.8 to 52.8
The consensus looks for no revision in the final from the
flash at 52.8 for October, up slightly from 51.9 in September.
US PMI Manufacturing Final for October (Mon 0945 EST;
Mon 1445 GMT)
Consensus Forecast, Index: 56.0
Consensus Range, Index: 56.0 to 56.0
As usual, forecasters see no revision in the October final
from the flash at 56.0. That is nearly flat from 55.9 in September. These
numbers indicate robust expansion in the face of surging price pressures.
US ISM Manufacturing Index for October (Mon 1000 EST;
Mon 1500 GMT)
Consensus Forecast, Index: 54.5
Consensus Range, Index: 53.9 to 55.0
The consensus sees the index unchanged at 54.5 in October
from 54.5 in September and from 54.6 in August, a remarkable run of steady
moderate expansion even with prices paid at elevated levels and going high and
higher.
US Construction Spending for October (Mon 1000 EST; Mon
1500 GMT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.1% to 0.6%
Construction spending expected up 0.5 percent, a big
increase for one month. That reflects the explosion in data center
construction.
Tuesday
South Korea CPI for October (Tue 0800 KST; Mon 2300
GMT; Mon 1800 EST)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.3% to 0.3%
Consensus Forecast, Y/Y: 2.9%
Consensus Range, Y/Y: 2.8% to 2.9%
Forecasters see CPI up 0.3 percent on the month and 2.9
percent on year in October, same as in September.
Australia RBA Announcement (Tue 1430 AET; Tue 0330
GMT; Mon 2230 EST)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 25 bp to 25 bp
Consensus Forecast, Level: 4.85%
Consensus Range, Level: 4.85% to 4.85%
Comments from RBA officials and recent above-target
inflation data signal the bank will raise rates again by 25 basis points.
US Motor Vehicle Sales for October (Any Time)
Consensus Forecast, Total Vehicle Sales - Annual Rate: 15.9
M
Consensus Range, Total Vehicle Sales - Annual Rate: 15.7
M to 16.0 M
Auto sales expected at a 15.9 million unit rate in October
compared with 16.0 million in September.
US Factory Orders for September (Tue 1000 EST; Tue
1500 GMT)
Consensus Forecast, M/M: 1.2%
Consensus Range, M/M: 1.1% to 2.6%
Higher than expected 1.8 percent increase in durable goods
orders already published for September augurs for similar 1.2 percent rise in
wider factory orders including nondurables.
US JOLTS for September (Tue 1000 EST; Tue 1500 GMT)
Consensus Forecast, Job Openings: 7.134 M
Consensus Range, Job Openings: 7.060 M to 7.225 M
Openings expected up slightly to 7.134 million in September
from 7.079 million in August.
Wednesday
New Zealand Labour Market Conditions for Third Quarter (Wed
1045 NZDT; Tue 2145 GMT; Tue 1645 EST)
Consensus Forecast, Q/Q: 0.5%
Consensus Range, Q/Q: 0.4% to 0.5%
Consensus Forecast, Y/Y: 1.6%
Consensus Range, Y/Y: 1.6% to 1.6%
Consensus Forecast, Unemployment Rate: 5.5%
Consensus Range, Unemployment Rate: 5.5% to 5.6%
The jobless rate is expected lower at 5.5 percent from 5.6
percent in the previous quarter as job growth has picked up enough to reduce
unemployment sightly.
Australia Household Spending for March (Wed1130 AET; Wed
0030 GMT; Tue 1930 EST)
Consensus Forecast, M/M: -0.3%
Consensus Range, M/M: -0.5% to 0.2%
Soft auto sales expected to weigh on overall household
spending.
China PMI Composite for October (Wed 0945 CST; Wed
0145 GMT; Tue 2045 EST)
Consensus Forecast, Services Index: 51.7
Consensus Range, Services Index: 51.4 to 51.7
Services index expected nearly unchanged at 51.7 in October
from 51.6 in September.
Sweden Riksbank Rate Decision for November (Wed 0930
CET; Wed 0830 GMT; Wed 0330 EST)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 25 bp to 25 bp
Consensus Forecast, Level: 2.0%
Consensus Range, Level: 2.0% to 2.0%
Hawkish comments from officials signal a rate hike at this
meeting and guidance for another rate increase by February. That is despite
better behaved inflation figures lately and a stronger currency.
France PMI Composite Final for October (Wed 0950 CET;
Wed 0850 GMT; Wed 0350 EST)
Consensus Forecast, Services Index: 48.4
Consensus Range, Services Index: 48.4 to 48.4
The consensus looks for no revision in the final from the
flash at 48.4 for services, showing contraction in October after tiny expansion
at 51.2 in September.
Germany PMI Composite Final for October (Wed 0955
CET; Wed 0855 GMT; Wed 0355 EST)
Consensus Forecast, Composite Index: 52.8
Consensus Range, Composite Index: 52.8 to 52.8
Consensus Forecast, Services Index: 51.7
Consensus Range, Services Index: 51.7 to 51.7
The consensus looks for no revision in the final from the
flash at 52.8 for the composite and 51.7 for services for October.
Eurozone PMI Composite Final for October (Wed 1000
CET; Wed 0900 GMT; Wed 0400 EST)
Consensus Forecast, Composite Index: 51.9
Consensus Range, Composite Index: 51.9 to 51.9
Consensus Forecast, Services Index: 51.7
Consensus Range, Services Index: 51.7 to 51.7
The consensus looks for no revision in the final from the
flash at 51.9 for the composite and 51.7 for services for October. That is down
from 53.1 and 53.0, respectively, in September.
UK PMI Composite Final for October (Wed 0930 GMT; Wed
0430 EST)
Consensus Forecast, Composite Index: 53.1
Consensus Range, Composite Index: 53.1 to 53.1
Consensus Forecast, Services Index: 53.1
Consensus Range, Services Index: 53.1 to 53.1
The consensus looks for no revision in the final from the
flash at 53.1 for both composite and services. That is up from 52.0 and 52.1,
respectively, in September. UK indicators have been creeping up.
Eurozone HICP for October (Wed 1100 CEST; Wed 1000
GMT; Wed 0500 EST)
Consensus Forecast, HICP - Y/Y: 3.9%
Consensus Range, HICP - Y/Y: 3.8% to 4.2%
Consensus Forecast, Narrow Core - Y/Y: 2.5%
Consensus Range, Narrow Core - Y/Y: 2.4% to 2.6%
Narrow core expected unchanged at 2.5 percent for October
from September. The total is seen higher at 3.9 percent versus 3.8 percent in
September as energy and commodity price increases kick in.
US ADP Employment Report for October (Wed 0815 EST;
Wed 1315 GMT)
Consensus Forecast, Private Payrolls - M/M: 70K
Consensus Range, Private Payrolls - M/M: 65K to 80K
Private jobs seen up 70K in October after 90K in September.
Canada Merchandise Trade for September (Wed 0830 EST;
Wed 1330 GMT)
Consensus Forecast, Balance: C$4.1 B
Consensus Range, Balance: C$3.5 B to C$6.3 B
The trade balance seen in surplus by a big C$4.1 billion in
September after C$4.2 billion in August with export values lifted by energy
price increases.
US International Trade in Goods and Services for
September (Wed 0830 EST; Wed 1330 GMT)
Consensus Forecast, Balance: -$107.9 B
Consensus Range, Balance: - $115.6 B to -$103.7 B
The gap is seen wider at a remarkable $107.9 billion in
September from $105.6 billion in August as AI buildout equipment flows in from
Asia.
US ISM Services Index for October (Wed 0945 EST; Wed
1445 GMT)
Consensus Forecast, Services Index: 54.7
Consensus Range, Services Index: 54.0 to 56.3
Another stable reading at 54.7 is the call, almost flat from
54.9 in September, as steady growth continues.
Thursday
Brazil Selic Rate for November (Thu 0630 BRT; Thu 0930
GMT; Thu 0430 EST)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 13.75%
Consensus Range, Level: 13.75% to 13.75%
After a rate cut last time, the Copom is expected on hold.
Australia International Trade in Goods for September (Thu
1130 AET; Thu 0030 GMT; Wed 1930 EST)
Consensus Forecast, Balance: A$1.0 B
Consensus Range, Balance: -A$1.0 B to A$2.5 B
Trade balance seen at a $1.0 billion.
Norway Norges Bank Rate Decision (Thu 0800 CET; Thu 0700
GMT; Thu 0200 EST)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 4.50%
Consensus Range, Level: 4.50% to 4.50%
The Norges bank is seen on hold and officials are expected
to express uncertainty over underlying inflation.
Sweden CPI Flash for October (Thu 0800 CET; Thu 0700
GMT; Thu 0200 EST)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.3% to 0.3%
Consensus Forecast, Y/Y: 1.4%
Consensus Range, Y/Y: 1.2% to 1.4%
Germany Manufacturing Orders for September (Thu 0800
CET; Thu 0700 GMT; Thu 0200 EST)
Consensus Forecast, M/M: 5.0%
Consensus Range, M/M: 3.0% to 6.0%
Consensus Forecast, Y/Y: 4.3%
Consensus Range, Y/Y: 3.3% to 4.3%
Orders are expected to rebound by 5.0 percent on the month
after dropping 10.6 percent in August.
France Industrial Production for September (Thu 0845
CET; Thu 0745 GMT; Thu 0245 EST)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: -0.2% to 0.5%
Output expected back up 0.5 percent on the month in
September after declining by 0.3 percent in August.
UK BoE Announcement and Minutes (Thu 1200 GMT; Thu
0700 EST)
Consensus Forecast, Bank Rate - Change: 25 bps
Consensus Range, Bank Rate - Change: 25 bps to 25 bps
Consensus Forecast, Bank Rate - Level: 4.0
Consensus Range, Bank Rate - Level: 4.0 to 4.0
The BOE is uniformly expected to go 25 bps in response to
rising energy costs even though second-round effects are hard to find. The big
question is what the bank says will happen next.
US Jobless Claims for Week of October 31 (Thu 0830 EST;
Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 196K
Consensus Range, Initial Claims - Level: 195 K to 200
K
Claims seen at 196K in latest week after 194K last week,
fairly stable at very low levels.
US Productivity and Costs for Third Quarter (Thu 0830
EST; Thu 1330 GMT)
Consensus Forecast, Nonfarm Productivity - Annual Rate:
3.0%
Consensus Range, Nonfarm Productivity - Annual Rate: 1.1%
to 3.8%
Consensus Forecast, Unit Labor Costs - Annual Rate: 1.1%
Consensus Range, Unit Labor Costs - Annual Rate: -0.1%
to 1.5%
Productivity seen up at a respectable 3.0 percent annual rate
in Q3 after 1.4 percent in Q2. ULC expected at 1.1 percent on year.
Friday
Germany Industrial Production for September (Fri 0800
CET; Fri 0700 GMT; Fri 0200 EST)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: -1.0 to 0.5%
Consensus Forecast, Y/Y: 1.9%
Consensus Range, Y/Y: 1.8% to 2.0%
The consensus sees industrial output up 0.5 percent on the
month and 1.9 percent on year in September.
Eurozone Retail Sales for September (Fri 1100 CET; Fri
1000 GMT; Fri 0500 EST)
Consensus Forecast, M/M: 0.0%
Consensus Range, M/M: -0.4% to 0.5%
Consensus Forecast, Y/Y: 0.6%
Consensus Range, Y/Y: 0.4% to 1.2%
The consensus sees another sluggish retail sales report with
no change in September from August and sales up only 0.6 percent from a year
ago.
Canada Labour Force Survey for October (Fri 0830 EST;
Fri 1330 GMT)
Consensus Forecast, Employment - M/M: 12 K
Consensus Range, Employment - M/M: 10K to 35K
Consensus Forecast, Unemployment Rate: 6.5%
Consensus Range, Unemployment Rate: 6.4% to 6.5%
A modest 12.2K increase is the call for employment with
unemployment rate flat at 6.5 percent in October from September, up from 6.4
percent in August.
US Employment Situation for October (Fri 0830 EST;
Fri 1330 GMT)
Consensus Forecast, Nonfarm Payrolls - M/M: 62K
Consensus Range, Nonfarm Payrolls - M/M: 40K to 100K
Consensus Forecast, Unemployment Rate: 4.2%
Consensus Range, Unemployment Rate: 4.2% to 4.3%
Consensus Forecast, Private Payrolls - M/M: 64K
Consensus Range, Private Payrolls - M/M: 35K to 65K
Consensus Forecast, Manufacturing Payrolls - M/M: 0K
Consensus Range, Manufacturing Payrolls - M/M: -2K to
12K
Consensus Forecast, Average Hourly Earnings - M/M: 0.3%
Consensus Range, Average Hourly Earnings - M/M: 0.2%
to 0.3%
Consensus Forecast, Average Hourly Earnings Y/Y: 2.9%
Consensus Range, Average Hourly Earnings Y/Y: 2.9%
to 3.0%
Jobs seen up a moderate 62K and the jobless rate flat at 4.2
percent in October.
US Consumer Sentiment for November (Fri 1000 EST; Fri
1500 GMT)
Consensus Forecast, Index: 47.5
Consensus Range, Index: 45.7 to 50.0
The first reading for November is expected to erode to 47.5
from 48.0 in October final and 48.1 in September and versus 51.0 in November
2025. Sentiment remains depressed by inflation concerns.
US Consumer Credit for September (Fri 1500 EST; Fri
2000 GMT)
Consensus Forecast, M/M: $ 11.5 B
Consensus Range, M/M: $5.0 B to $12.0 B
A plain vanilla monthly increase of $11.5 billion is the
call for consumer credit outstanding in September from August.
|